 Free
See it all. Pay it off. Own what's next.
Every debt you owe.
One page. One date you're done.
Free & Clear builds your household's complete debt ledger from your real credit reports — including the debts you forgot you had — sorts out what you don't actually owe, and hands you a dated, month-by-month plan to zero. Most families find money in the first hour.
Planning & budgeting education. We never touch your money, never negotiate with your creditors, never promise a credit score. Every number traces to your documents.
The problem, named the way you feel it
- You make good money. So why does it feel like you're running in place?
- You've got cards, a couple of "interest-free" plans, a buy-now-pay-later habit split into a dozen tiny loans, a car that's worth less than the loan — and no single page anywhere that adds it all up.
- You've never seen the real total. Neither has your partner. That's not a character flaw — it's a missing system.
- Meanwhile the minimums-only path quietly costs the average household we model tens of thousands in interest — and never actually ends.
The traps hide in plain sight. Our intake hunts them on purpose:
BNPL clusters
Buy-now-pay-later loans split into a dozen tiny plans — easy to forget, all still due.
Deferred-interest cliffs
"Interest-free" promos that charge every cent of back interest if a balance survives the promo end date.
Debts that aren't yours
Authorized-user accounts, old charge-offs, errors — listed on your report, not yours to pay.
Minimums only
In our founding household's model, paying only minimums never actually ends — balances still alive a decade out, and $70,000+ in interest paid along the way. The total payment also quietly shrinks as small balances die, which is exactly how the timeline stretches forever.
One payment, held steady
The same household on a single fixed monthly payment — every spare dollar aimed at the highest-rate target, each dead debt's payment rolling into the next — is debt-free in 28 months at roughly $19,600 of interest. Same income. Same debts. The difference is the system.
What we found in our first household
$186K earned. $220K owed. 29 payment plans they'd missed.
Our founding household earned $186K and owed $220K. Their own list of debts missed 29 small payment plans and an entire credit card. Over $53,000 on their reports turned out to be money they didn't owe at all — an authorized-user account and old items being removed.
With everything finally on one page, they picked their speed: debt-free in 28 months, then the same payment builds a $75,000 war chest for buying a business.
Their chosen plan, milestone by milestone:
- Cards + BNPL gone — first summer of the plan
- Then the big secured lines, one at a time — vehicle and tax lines cleared in order
- Debt-free — 28 months after start, roughly $19,600 in total interest instead of $70,000+
- The same payment flips to savings — a $75,000 war chest about nine months later
Founding household results; your numbers will differ — that's the point of building yours.
How it works — The Debt Freedom System
See It All
Both partners' reports + statements become one verified ledger. Nothing counted twice.
Sort the Piles
What you owe vs. what can be removed. The $0 pile is most families' fastest win.
Stop the Leaks
Autopay audit, late-fee kills, the BNPL freeze, promo-cliff dates on the calendar.
Pick Your Speed
Good / Better / Best, modeled month by month. You choose with your eyes open.
Run It
Monthly 15-minute reviews against your model. Adjust calmly, never abandon.
Flip It
The same payment becomes savings, then ownership.
Phases 1–4 can be carried through in a single working session once your documents are in. Read the full system →
What lands in your hands
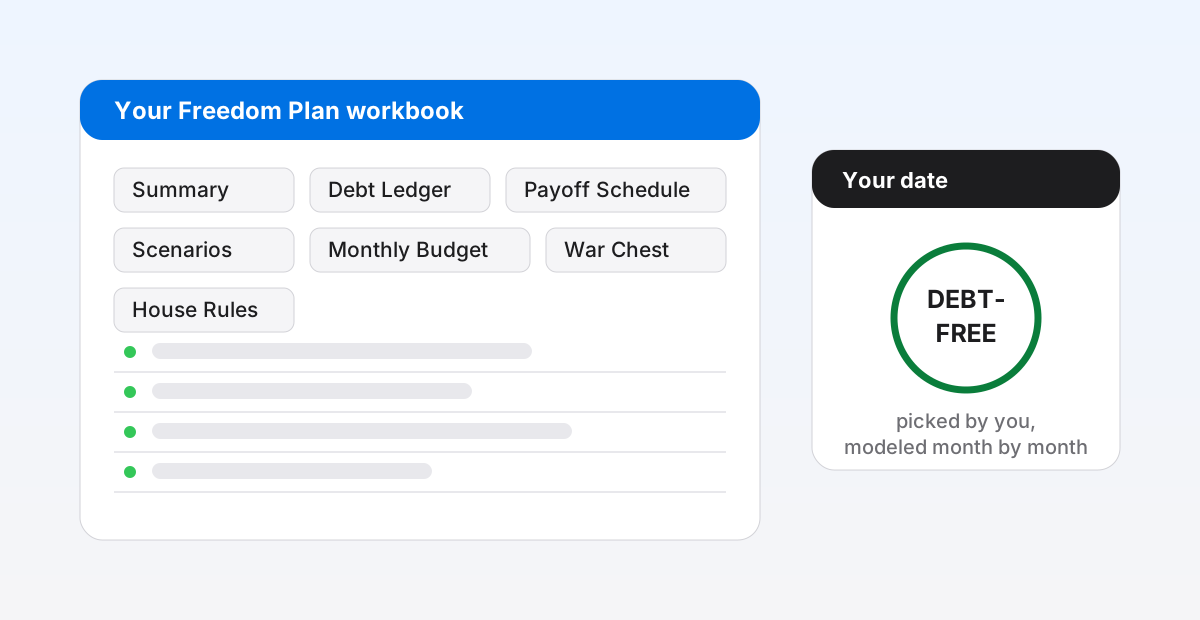
The verified ledger
Every account, owner, balance, payment and rate — each traced to a document or labeled an estimate, each counted exactly once.
The $0-pile sort
What isn't yours to pay, itemized with its removal action — and a re-pull date 30–45 days out to prove the deletion.
Three speeds, modeled
Good / Better / Best, month by month: debt-free date, total interest, and milestone dates for each — beside the minimums-only baseline.
Your workbook + calendar
The plan as a workbook both partners can open any time, plus promo-cliff and milestone dates on the calendar — and a delivery session to pick your speed and start date.
The offers
The Freedom Kit
$79
DIY: templates, trap checklist, house rules, workbook. Start tonight.
Get the Kit — $79Core offer
The Freedom Plan
$497
We build it all for you and deliver your custom workbook + a session to pick your speed and start date.
Founding cohort: first 10 families, $297.
Founding Cohort — $297 Freedom Plan — $497Run It With Us
$99/mo
Monthly reviews, re-models, milestone tracking. Cancel anytime.
Run It With Us — $99/moFreedom + Ownership Track
$1,497
For families aiming past free: war chest + business-acquisition roadmap.
Ownership Track — $1,497Secure checkout via Stripe. Planning & budgeting education — not licensed financial, tax, or legal advice.
Who this is for — and who it isn't
For: two-income households, $100K+ income, $50K+ in mixed debt, tired of guessing.
Not for: anyone looking for a quick fix, a settlement mill, or someone to "make it go away." We don't do that. We build the map — you drive it, and it works.
The house rules every family runs on
- One war payment, every month, never stepping down.
- Autopay everything; a late fee is a plan failure, not a life event.
- No new debt until free — no cards, no BNPL, no exceptions.
- Lump sums go 100% to the current target the day they land.
- Fixed lines (tax plans, family loans, locked terms) stay current and untouched.
- Never sell a vehicle underwater or roll negative equity. Break-even first, decisions second.
- Removals are tracked, not paid. Prove deletion on the re-pull.
- Review monthly, adjust calmly, never abandon.
How it starts
- Intake. A short conversation and a document list — both partners' credit reports and recent statements. We show you exactly how to pull them.
- The ledger gets built. Every number verified to a document, every account counted once, the traps flagged.
- The piles get sorted. What you owe separated from what you don't — with removal actions for the $0 pile.
- Leaks plugged, speeds modeled. Your leak list, attack order, and Good / Better / Best side by side.
- Delivery session. We walk the ledger, the piles, and the scenarios together. You pick your speed and your start date.
- Day 1 and beyond. Workbook and house rules in hand, first payments scheduled, monthly 15-minute reviews on the calendar.
Ledger + scenarios land within 5 business days of complete documents.
Both partners' credit reports
All three bureaus, for both of you. Joint and authorized-user accounts show up twice across two files — the reports are how we catch what memory misses, and how we prove what's counted once.
Every statement
Cards, vehicle loans and leases, tax installment plans, family loans, and every buy-now-pay-later plan — if it has a payment, it has a statement, and it goes on the page.
One honest conversation
Income, the fixed lines, and the stuff that never made it onto a report. No judgment and no lecture — the numbers are the numbers, and the plan is built from yours.
FAQ
Is this financial advice?
No — it's budgeting and planning education built from your documents. Tax, legal, or bankruptcy questions get referred to licensed professionals.
Do you contact my creditors or take over payments?
Never. Your money never touches us.
Will this fix my credit score?
We don't sell credit repair. Families usually see scores improve as utilization falls and errors get removed through proper channels — but the product is the plan, not a score promise.
What do you need from us?
Both partners' credit reports (we show you how to pull them), recent statements, and one honest conversation.
What if some of it isn't our debt?
That's the first thing we sort — it's Phase 2, and for many families it's worth thousands.
How fast do we get the plan?
Ledger + scenarios within 5 business days of complete documents.
Kit or Plan — which one?
The Kit is the same system as a do-it-yourself workbook: templates, trap checklist, house rules. The Plan is us building it for you — verified ledger, pile sort, leak list, three modeled speeds, and the delivery session.
What happens at the monthly review?
Fifteen minutes: actual balances against your model's schedule. Ahead, on, or behind — we adjust calmly and re-model when life changes. Milestones get marked on schedule, and removals get verified on a re-pull.
Your debt already has a total.
You just haven't seen it yet.
Get My Freedom Plan
Founding cohort pricing ends at 10 families.